This article is based on tax law for the year ending 28 February 2025.
Question:
The client received R10 million in 2008 from the sale of land, which was invested in a trust. However, the previous accountant incorrectly disclosed the investments in the client's individual financials instead of the trust's financials. The client is now concerned about potential tax liabilities, such as fringe benefit interest, corporate tax, and dividend withholding tax (DWHT). They are seeking guidance on whether to disclose everything through the Voluntary Disclosure Programme (VDP) and how to minimise the implications.
Answer:
1. Incorrect Disclosure of Investments in the Client’s Individual Financials Instead of the Trust
- Issue Identified: Investments held in the trust (e.g. endowment policies) were incorrectly disclosed in the individual’s financials, potentially leading to non-compliance and penalties for understated income.
- Action Required: Correct the financial records by updating them to reflect the trust as the holder of these investments. Amended tax returns may be necessary.
- Relevant Legislation: Section 25B of the Income Tax Act 58 of 1962 governs the taxation of income retained or distributed by a trust.
2. Loan Accounts from the Sale of Land and Fringe Benefit Taxation
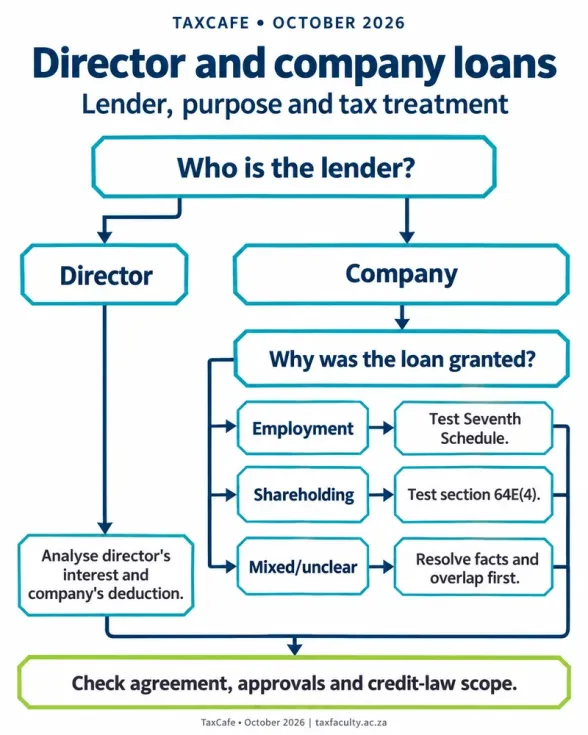
- Issue Identified: R5 million loan accounts were created post-sale of the land in 2008, but no interest or fringe benefits tax has been accrued. According to Section 7C of the Income Tax Act, interest-free loans between connected parties (including trusts) are subject to deemed donation tax.
- Action Required: Calculate the deemed donations tax on unpaid interest from 2017 (when Section 7C came into effect). Assess any exemptions related to trust expenses.
- Relevant Legislation: Section 7C of the Income Tax Act addresses deemed donations on interest-free or low-interest loans to trusts.
3. Deregistered Companies and Associated Tax Compliance
- Issue Identified: The companies involved in the loan accounts have been deregistered with CIPC and are likely inactive with SARS. They haven't filed Annual Returns or Tax Returns since 2008.
- Action Required: Reregister the companies with CIPC and reactivate their tax status with SARS. Submit outstanding Annual Tax Returns and correct financial disclosures, including income tax on the deemed interest from the loans.
- Relevant Legislation: SARS may impose administrative penalties under Section 213 of the TAA for failing to submit returns.
4. Dividends Withholding Tax (DWHT)
- Issue Identified: To clear the loan accounts, declaring dividends may be necessary, but this will attract DWHT at 20%. Additionally, SARS will assess DWHT on the gross dividend distributed.
- Action Required: Declare dividends to clear the loan accounts, ensuring DWHT is withheld and paid to SARS on time to avoid penalties and interest.
- Relevant Legislation: Sections 64D to 64N of the Income Tax Act outline DWHT obligations on dividend distributions.
5. Voluntary Disclosure Programme (VDP)
- Issue Identified: Non-compliance could lead to penalties for fringe benefit interest, DWHT, and corporate tax on the deemed interest from the loans.
- Action Required: Use the VDP to disclose:
- DWHT on the R10 million dividend distribution
- Fringe benefit tax on the loans
- Trust-related Section 7C obligations retrospectively
- Ensure full and truthful disclosure to benefit from relief under the Tax Administration Act (TAA), Section 227.
- Relevant Legislation: Section 227 of the TAA provides relief from understatement penalties and criminal prosecution for voluntary disclosures. Section 223 sets out potential understatement penalties.
6. Potential Tax Liabilities
- Issue Identified: The retrospective calculation of fringe benefit interest (16 years), deemed interest tax under Section 7C, and DWHT could result in total liabilities exceeding R6 million.
- Action Required: Engage with SARS to estimate the full liability, including interest calculations based on historical prime rates. Negotiate a payment plan if necessary.
7. Recommendations
- Determine Tax Liability: Identify all underdeclared taxes for all entities involved.
- Submit VDP: Include all non-compliance issues (fringe benefit interest, DWHT, trust-related donations tax under Section 7C) to minimise penalties and ensure relief from criminal liability.
- Reregister Companies: Reactivate the deregistered companies with CIPC and SARS to ensure compliance and settle DWHT and corporate tax obligations.
- Correct Trust Reporting: Ensure the trust is properly disclosed as the holder of the investments to avoid penalties for incorrect past disclosures.
- VDP Approach: Manage the VDP carefully, covering all entities involved. An anonymous VDP application is recommended.
Frequently asked questions
What was the core disclosure error after the land sale?
Investments held in a trust were incorrectly shown in the individual's financials instead of the trust's, creating understated-income and compliance risk.
Why does section 7C feature in the loan-account analysis?
Interest-free or low-interest loans to trusts by connected persons can trigger deemed donations from the effective date of section 7C, so unpaid interest must be quantified.
What should happen to the deregistered companies linked to the loans?
They should be reregistered with CIPC, tax status reactivated with SARS, and outstanding returns filed so disclosures and liabilities can be corrected.
Why is a Voluntary Disclosure Programme application recommended?
To bring DWHT, fringe-benefit or loan-related exposure, and section 7C issues into one truthful disclosure and seek relief from understatement penalties and criminal prosecution under the TAA.