This article is based on tax law for the year ending 29 February 2025.
Question:
A foreign company employs South African residents to deliver services to its customers in the foreign country where it is registered. The employment contracts are with the foreign company. The company is now renting an office in South Africa for employees to work from a central location and has registered an external company. The external company will incur the office costs and recover these costs from the foreign entity. The foreign entity has registered for PAYE. Will there be any other tax implications, given that the external company will not receive income except for the recovery of office costs?
Answer:
1. The Problem / Facts
A foreign company employs South African residents to provide services for its business operations abroad. It has registered an external company in South Africa, which will manage office-related expenses, with these costs being recovered from the foreign company. While the foreign entity has registered for PAYE for its employees, the external company will not generate income beyond cost recovery. The question concerns any potential tax implications for the external company arising from this arrangement.
2. Applicable Law
Income Tax: The recovery of costs by the external company from the foreign entity may fall under consideration in terms of Sections 1 (definition of "gross income") and 11(a) (deductibility of costs) of the Income Tax Act 58 of 1962.
-
Transfer Pricing:
- Transactions between the foreign company and the external company may be subject to Section 31 of the Income Tax Act 58 of 1962, which governs transfer pricing and the arm’s length principle.
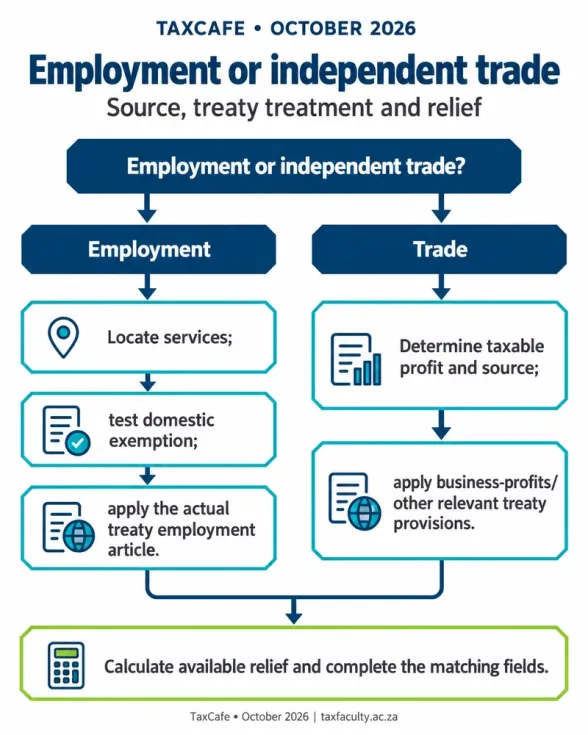
- Permanent Establishment (PE) and Tax Residency: The presence of a rented office and employees working centrally in South Africa may create a PE for the foreign company under the provisions of applicable Double Taxation Agreements (DTAs) and Section 1 of the Income Tax Act.
- VAT (Value-Added Tax): If the external company’s recoveries exceed the VAT registration threshold, it may be required to register for VAT in terms of the VAT Act 89 of 1991.
3. Application of the Law to the Facts
-
Income Tax (Gross Income and Tax Deductibility):
-
The cost recoveries may be regarded as "gross income" under Section 1, as they represent receipts in the external company’s hands, even if no profit is made. However, these recoveries may be offset by deductions under Section 11(a), provided they directly relate to the company's business expenses.
-
-
Transfer Pricing:
-
If the foreign entity and the external company are related, SARS may assess whether the cost recoveries comply with the arm’s length principle under Section 31 of the Income Tax Act.
-
-
Permanent Establishment (PE):
-
A rented office in South Africa and employees working from a central location may create a PE for the foreign company under relevant DTAs. This could result in the foreign company having to declare South African-sourced income attributable to the PE, even if the external company only recovers expenses.
-
-
VAT:
-
If the external company’s cost recoveries exceed R1 million per annum, it may need to register for VAT under Section 23 of the VAT Act, even if the transactions are purely cost recoveries.
-
4. Summary
- It is essential to assess whether the external company contributes to the generation of income. If so, this income may be attributed to the external company, with expenses incurred in its production being deductible. Corporate Income Tax (CIT) would then be payable on the deemed taxable income or profit.
Frequently asked questions
Are pure cost recoveries still gross income for the external company?
They may be receipts under the gross-income definition even without a profit mark-up, though matching section 11(a) deductions can offset them where the costs are deductible.
Why does transfer pricing matter between the foreign company and the external company?
Related-party recoveries can be tested under section 31 for arm's-length pricing.
Could the foreign company create a South African permanent establishment?
A rented local office with staff working from that base may create a PE under the Income Tax Act and applicable treaty rules, with income attribution consequences.
What other registration risk sits with cost recoveries?
If recoveries are large enough, VAT registration may be required even where the external company only recovers office costs.