




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Distinguishing foreign employment from independent consulting
- 28 October 2026
- International Tax
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Income category |
Main enquiry |
Frequent error |
|
Employment remuneration |
Section 10(1)(o)(ii) conditions and treaty |
Assuming foreign payment is enough |
|
Independent consulting |
Trading profit, source and treaty |
Applying an employee exemption |
|
Short foreign assignment |
Treaty employment conditions |
Treating 183 days as a standalone holiday |
|
Codes 4222/4223 |
Foreign trading profit/loss classification |
Allowing the code to decide the law |
A South African resident working for a foreign customer may be an employee, an independent consultant or the owner of a business providing services through a company. These arrangements can look similar in a bank statement and receive different tax treatment.
Practitioners should classify the relationship, establish residence and source, apply domestic law and then consider the relevant treaty. These steps determine the income and relief to disclose. A return code selected before that analysis can obscure the difference between employment remuneration and trading profit.
Apply the employment exemption to employment income
Section 10(1)(o)(ii) of the Income Tax Act 58 of 1962 applies to qualifying remuneration for employment services rendered outside South Africa. It requires the relevant absence periods: more than 183 full days in aggregate during a qualifying 12-month period, including a continuous period exceeding 60 full days. The exemption is limited to R1.25 million per year of assessment and remains subject to the provision’s other conditions. Independent trading income does not acquire this exemption merely because the taxpayer worked abroad. SARS: foreign employment income exemption.
The contract’s label is relevant but not decisive where the conduct contradicts it. Establish who controls the work, what obligations exist, how remuneration is determined and whether the individual carries on an independent trade. The source of employment income generally follows where the services are performed, rather than the payer’s address.
Illustrative example. Assume a resident employee earns R1.6 million entirely for qualifying foreign services and satisfies all exemption conditions. The R1.25 million cap leaves R350 000 outside that exemption, before any other relevant relief or adjustments. A consultant invoicing the same R1.6 million cannot use that calculation simply because the invoices were sent abroad.
Client conversation trigger: Review clients described as “foreign contractors” who have claimed the employment exemption and reconcile their contracts with the services actually performed.
Read every condition in the treaty article
A treaty’s employment article may preserve exclusive residence-state taxation for a short assignment only if all its conditions are met. These commonly concern presence, the employer’s residence and whether remuneration is borne by a permanent establishment in the host state. The precise period and wording vary by treaty. “Less than six months” is therefore an inadequate instruction.
Business profits require a different analysis. Article 7 commonly deals with profits attributable to a permanent establishment, but some treaties contain separate independent-personal-services provisions or service-related permanent-establishment rules. The relevant treaty, protocol and applicable Multilateral Instrument modifications must be read before applying a general model.
For example, a short stay may still fail a treaty employment exemption if the remuneration is paid by a host-country employer or borne by the relevant host-country permanent establishment. Conversely, a customer’s presence in another country does not by itself establish that a consultant has a permanent establishment there. Domestic taxing rights and treaty restrictions must be considered in order. SARS: double taxation agreements and protocols.
Client conversation trigger: For each cross-border assignment, obtain the cost-bearing arrangement as well as the employment contract and travel calendar before promising treaty exemption.
Reconcile the return to the legal conclusion
Where codes 4222 and 4223 appear for foreign trading profit and loss, their use must follow the trading-income classification. They cannot substitute for an employment-income analysis. Check the current return’s description, the taxpayer’s category and the supporting computation before capture. A foreign customer does not necessarily make a trade conducted in South Africa foreign-source.
The South African Revenue Service (SARS) may already hold third-party information, but pre-population does not settle the classification. A return should disclose gross income, deductions, exempt amounts and foreign taxes in their correct places. Where foreign tax was withheld contrary to a treaty, the appropriate remedy may include a foreign refund process; it should not be assumed that South Africa must credit every amount withheld.
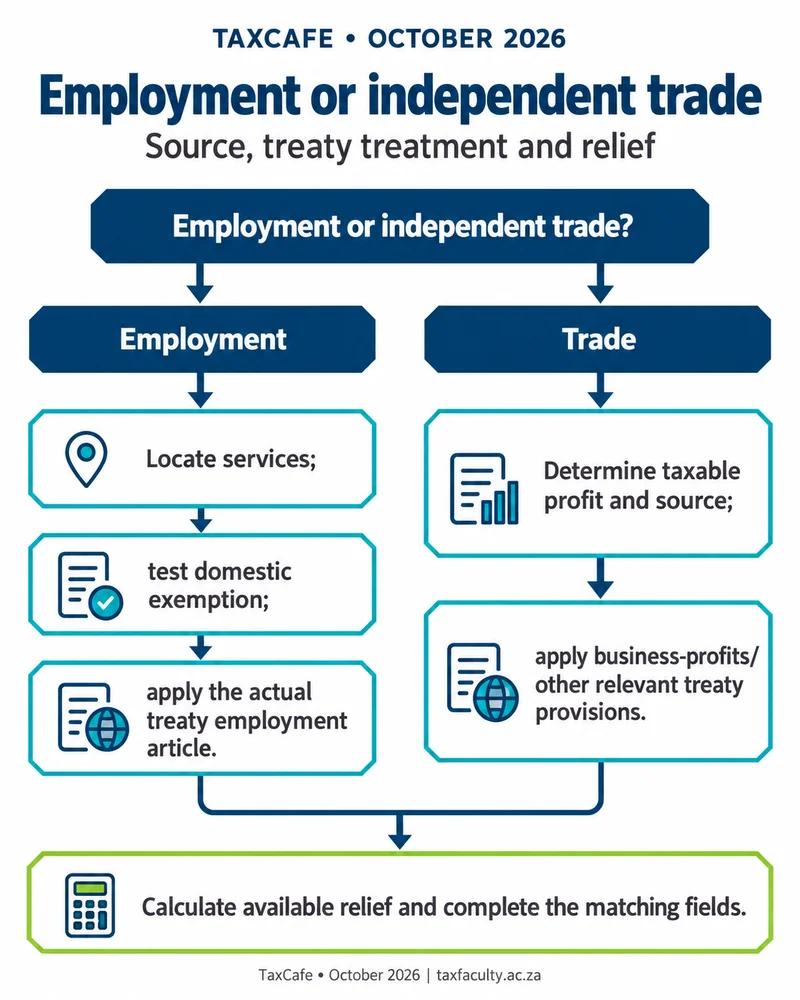
The final file should explain why the classification was adopted, how the day count was calculated and how relief was limited. Retain it with the submitted return and assessment so that the captured fields can be traced to the computation.
Client conversation trigger: Reconcile foreign withholding certificates to the same income and period used in the South African computation, and identify any tax that must be recovered abroad.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Status |
Employee or trader |
Cross-border workers |
Review contract and conduct |
Before advice |
|
2 |
Exemption |
Days, services and cap |
Resident employees |
Prepare day and income schedules |
Each tax year |
|
3 |
Treaty |
Multiple conditions |
Foreign assignments |
Read applicable treaty and cost allocation |
Before departure |
|
4 |
Return |
Codes and relief |
All foreign earners |
Match fields to legal computation |
Before filing |
Record the classification, qualifying services and applicable relief before completing the return. Reconcile foreign withholding and the return fields to that conclusion so that each amount can be explained.
Related reading: Protecting the tax position when foreign income fields change; Testing the tax exemption for seafarers and yacht crew; Defining representative roles for nonresident clients.
Frequently asked questions
Who qualifies for the foreign employment income exemption?
Section 10(1)(o)(ii) applies to remuneration for employment services rendered outside South Africa. It requires more than 183 full days abroad in a 12-month period, including a continuous period exceeding 60 full days.
How much foreign employment income is exempt?
The exemption is limited to R1.25 million per year of assessment and remains subject to the provision’s other conditions.
Can an independent consultant working abroad claim the exemption?
The exemption applies to employment income, not trading profit. Establish who controls the work, how remuneration is determined and whether the individual carries on an independent trade, because a contract label is not decisive.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s Professional Certificate in International Taxation.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).