


This ruling determines the tax consequences for the Applicants following the proposed distribution by a holding company of shares in an intermediate holding company to its shareholders in terms of the de-grouping rules in section 45(4).
Source: SARS
This ruling determines the tax consequences for the Applicants following the proposed distribution by a holding company of shares in an intermediate holding company to its shareholders in terms of the de-grouping rules in section 45(4).
Source: SARS
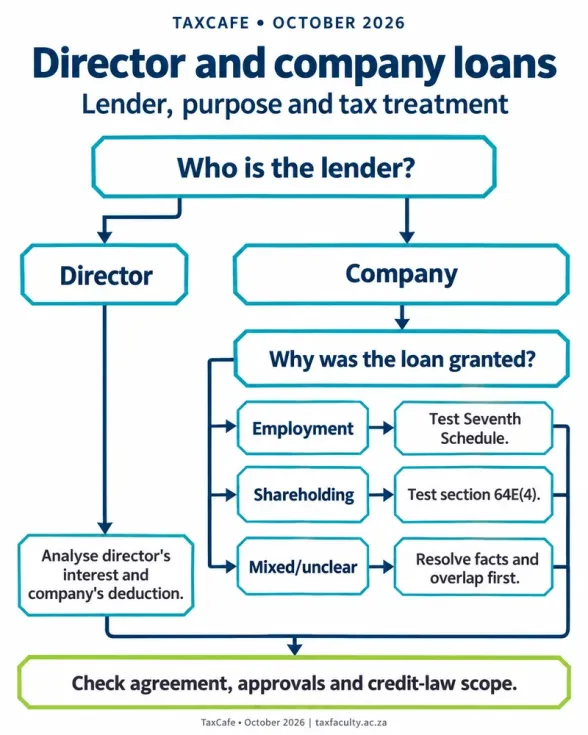
A debit director’s loan account and a credit director’s loan account are opposite transactions. In o...
Group businesses frequently support one another through direct supplier payments, advances and fundi...
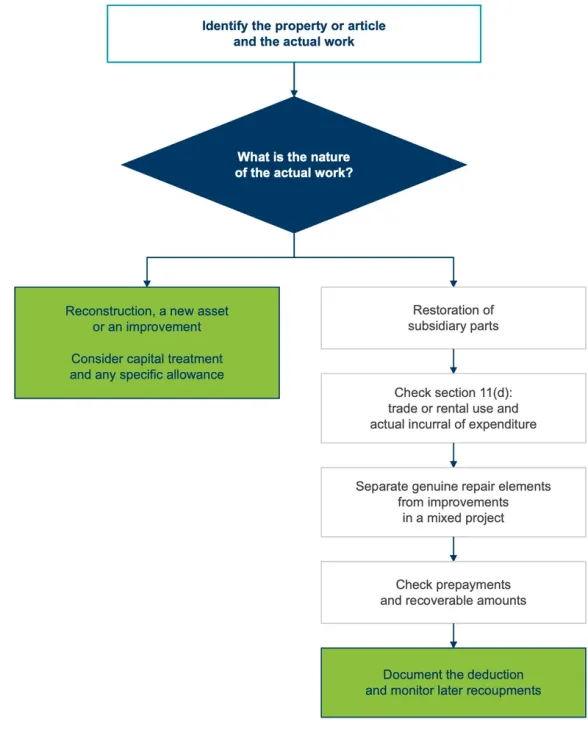
The description “repairs and maintenance” in a ledger is a starting point, not a tax conclusion.