




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Allocating rental income after the death of a landlord
- 28 October 2026
- Individuals Tax
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Period or event |
Taxpayer/enquiry |
Main control |
|
Before and up to death |
Deceased person's final period |
Establish receipts and accruals |
|
Estate administration |
Separate deceased-estate income enquiry |
Use estate records and reference |
|
Beneficiary entitlement |
Identify when and in what capacity income accrues |
Read the will and distribution documents |
|
Asset passing at death |
Sections 9HA and 25 |
Review deemed disposal and exceptions |
|
Estate duty |
Separate Estate Duty Act calculation |
Do not substitute for income-tax returns |
Rent does not cease to have a tax character when the landlord dies. The practitioner must identify the period of entitlement and the person to whom the income belongs. The date on which the tenant happens to pay is only part of that enquiry.
Prepare a chronology covering the deceased person’s final tax period, the estate’s administration and the beneficiary’s entitlement. Reconcile rent and expenses across those stages before completing the returns. The same record helps identify prior-year income incorrectly repeated in the final assessment.
Establish the two income tax periods and the correct references
For the current statutory regime, section 25 of the Income Tax Act 58 of 1962 treats relevant income received or accrued in the executor’s capacity as income of the deceased estate. The deceased person’s final return covers the period ending at death, while the estate’s post-death affairs require their own treatment and, where applicable, registration and returns.
Report the death to the South African Revenue Service (SARS), establish the executor’s authority and confirm the registration particulars. The deceased’s reference and the estate’s reference should not be used interchangeably. The relevant SARS guide explains the return processes and the distinction between pre-death and post-death affairs. SARS: ITR12 guide for deceased and insolvent estates.
Obtain the lease, rent ledger, bank statements and debtor balances at death. An amount that accrued before death but is collected afterwards requires reconciliation so that it is not simply taxed twice. Similarly, a late bank deposit should not automatically be allocated to the estate’s income merely because it arrived after death.
Client conversation trigger: On notification of a landlord’s death, obtain a cut-off rent and expense ledger before accounts are combined or bank access becomes difficult.
Establish when the beneficiary becomes entitled to income
A beneficiary named in a will does not necessarily earn all post-death rent from the moment of death. Identify the estate’s legal position, the beneficiary’s rights and when the property or income entitlement is distributed or otherwise passes. The estate is not automatically a trust through which current income is vested by a trustee resolution under section 25B.
Illustrative example. Assume a lease provides that rent accrues daily at R1 000 a day. The sole landlord dies after the fifteenth day of a 30-day month, and the facts place the remaining period’s income in the estate. The starting allocation is R15 000 to the deceased’s period and R15 000 to the estate. If the lease instead creates an unconditional entitlement to the whole month’s rent before death, a simple daily split may be wrong. The contract and accrual rules must be examined.
Marriage in community of property introduces a further allocation enquiry. The surviving spouse’s rights and the administration of the joint estate must be considered; the executor’s control of an account does not mean all income in it belongs exclusively to the deceased estate. SARS: deceased-estate FAQs.
Client conversation trigger: Before allocating post-death rent to heirs, compare the will, matrimonial regime, estate accounts and the actual date on which entitlement passes.
Reconcile assessments and distinguish the taxes arising at death
Section 9HA of the Income Tax Act addresses deemed disposal at death, with specified exceptions, including relevant surviving-spouse treatment. Section 25 addresses the estate’s acquisition and later disposal treatment. These rules should be applied to the property and its intended destination, rather than assuming every asset receives the same market-value uplift. SARS: Interpretation Note No. 134.
Estate duty under the Estate Duty Act 45 of 1955 is a separate calculation. Completing an estate-duty return does not complete the deceased’s or estate’s income-tax obligations. The same asset may be relevant to more than one calculation for different reasons.
An asset awarded to an heir or legatee generally passes out of the estate on the tax-neutral basis prescribed by section 25(3), with the heir taking the corresponding expenditure amount. That is different from an executor selling the asset to a third party. Section 25(3)(c) fixes the estate’s disposal to the heir at the earlier of the disposal date and the date the liquidation and distribution account becomes final. Record that finalisation date; registration of transfer is not the only relevant event.
Where an assessment appears to pull earlier income into the death year, reconcile the third-party certificate, accrual period, earlier return and current assessment. Identify a duplicated amount precisely. If the earlier treatment was wrong, the solution may require correcting that period as well; it is not always appropriate simply to delete the amount from the final return.
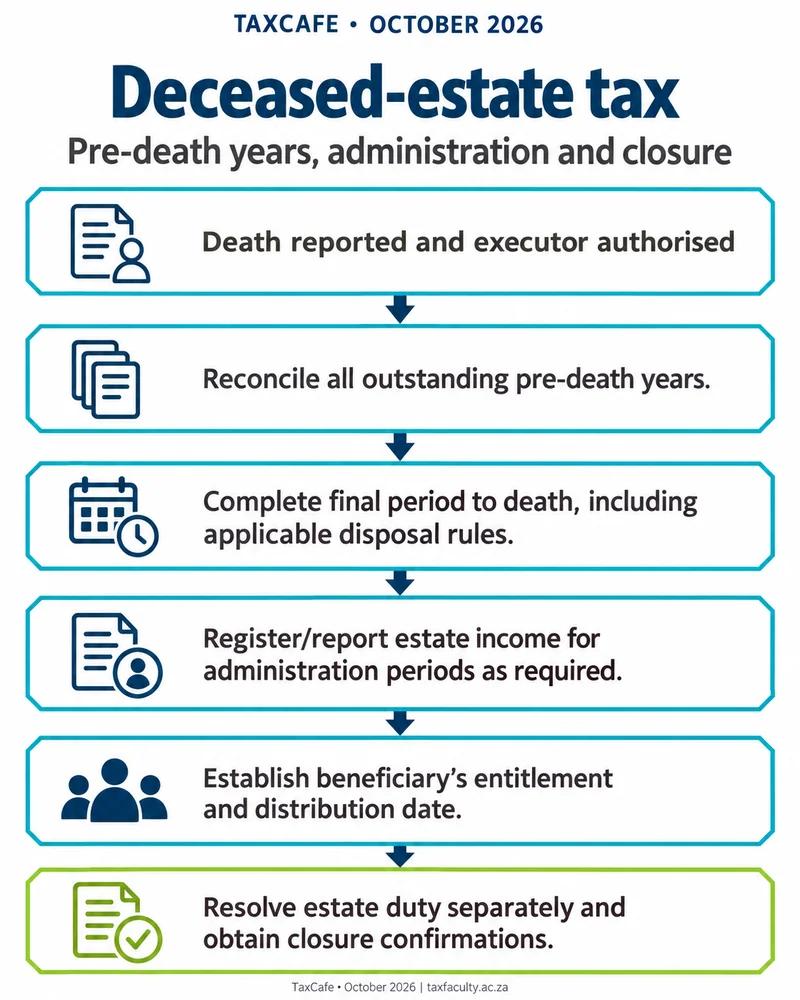
The closing file should contain the allocation schedule, supporting legal documents and accepted assessments. This allows the executor and beneficiary’s practitioner to use the same factual basis and prevents income from being omitted between them.
Client conversation trigger: Agree a shared allocation schedule with the executor and beneficiary’s adviser before either files returns relating to the same rental stream.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Registration |
Deceased versus estate |
Executors |
Confirm authority and references |
On death |
|
2 |
Cut-off |
Receipt and accrual |
Rental estates |
Prepare dated ledger allocation |
Before returns |
|
3 |
Beneficiary |
Passing of entitlement |
Heirs and spouses |
Review legal documents |
Before allocation |
|
4 |
Tax types |
Income tax, capital gains and estate duty |
Estates |
Prepare separate calculations |
During administration |
|
5 |
Assessment |
Prior-year duplication |
Affected returns |
Reconcile certificates and years |
On assessment |
Agree the income allocation with the executor and the beneficiary’s adviser, and retain the documents showing when entitlement passed. Use that schedule consistently across the relevant returns and estate records.
Related reading: Allocating rental income between spouses; Testing deductions and losses on family rentals; Completing a passive trust return without omitting its affairs.
Frequently asked questions
Who pays tax on rental income after the landlord dies?
The deceased person’s final return covers the period ending at death. Under section 25 of the Income Tax Act, income received or accrued in the executor’s capacity is income of the deceased estate, and the beneficiary is taxed once entitled to the income.
Does the date the tenant pays decide who is taxed on the rent?
No. The practitioner must identify the period of entitlement and the person to whom the income belongs, and the payment date is only part of that enquiry.
Can the deceased’s tax reference be used for the estate?
No. The deceased’s reference and the estate’s reference should not be used interchangeably. Report the death to SARS, establish the executor’s authority and confirm the registration particulars.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s Short Course in Estate Duty and Donations Tax.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).