




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Protecting the tax position when foreign income fields change
- 28 October 2026
- International Tax
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Problem |
First question |
Immediate control |
|
Foreign income disappears |
Was it saved, submitted and assessed? |
Preserve each version |
|
Exemption disappears |
Does the taxpayer substantively qualify? |
Maintain an independent computation |
|
Residence status changes |
What facts and decision support the change? |
Obtain the notice and effective date |
|
UK relocation |
Which domestic and treaty tests apply? |
Prepare a two-country chronology |
A return that appears correct on screen may produce a different saved version or assessment. Where foreign income or an exemption is involved, the discrepancy can be material. The practitioner needs to establish what the taxpayer should declare and what the system actually received.
Practitioners reported disappearing foreign-income fields and changes in recorded residence status at the 23 October 2026 TaxCafe webinar. Each affected return still requires its own diagnosis. Compare the saved, submitted and assessed information against an independent tax computation before attributing the difference to software.
Prepare an independent residence and income computation
Residence under section 1 of the Income Tax Act 58 of 1962 is a legal conclusion drawn from the facts and, where applicable, a double taxation agreement. Residents generally fall within a worldwide-income basis; non-residents require a South African-source analysis. Citizenship, immigration permission, a foreign address and tax residence are distinct matters.
Prepare a schedule identifying each income stream, the person earning it, where the services were performed, the period of accrual, currency conversion and the basis of any exemption or foreign-tax credit. Use that schedule to check the return after any change in the wizard or available fields.
For a client who ceased to be resident, preserve the submitted declaration, supporting documents, South African Revenue Service (SARS) correspondence and effective date. Revisit the substantive position if the facts change. A client may genuinely re-establish South African residence; an unexplained profile change may instead be an administrative mismatch. SARS: cessation and reinstatement of residence.
Client conversation trigger: For every client claiming non-resident treatment, maintain a dated residence memorandum and the SARS correspondence supporting the recorded effective date.
Treat a UK move as a coordinated two country exercise
A move to the United Kingdom does not create a universal “six-month tax holiday”. Domestic residence rules must be considered in both countries. If both regard the individual as resident, the applicable treaty tie-breaker requires its own factual analysis. The employment-income article then addresses taxing rights over remuneration; it is not the residence test.
The UK–South Africa treaty must be read with the 2010 Protocol and applicable modifications under the Multilateral Instrument. The published synthesised text assists with that reading. Practitioners should use the version relevant to the period concerned rather than an unamended treaty downloaded years earlier. HMRC: synthesised UK–South Africa treaty.
Prepare a calendar of workdays, travel, homes available, family movements and employment changes. The countries’ tax years do not align, so a foreign assessment may not map directly to a South African return. Foreign tax paid should be traced to the same income and relevant period before calculating relief. Departure may also require an exit-charge analysis under section 9H of the Income Tax Act; changing the residence field is not the whole compliance exercise.
Client conversation trigger: For UK-bound or returning clients, coordinate both tax-year calendars and obtain foreign payroll and assessment records before calculating South African relief.
Prove the system discrepancy and protect the remedy
Capture the return before saving, reopen it, inspect the calculation and retain the submitted version and assessment. Record the tax year, field, amount, time and exact error. A useful query says that a specified R-value in a specified field disappeared between two identifiable stages. “Foreign income is broken” is much harder to investigate.
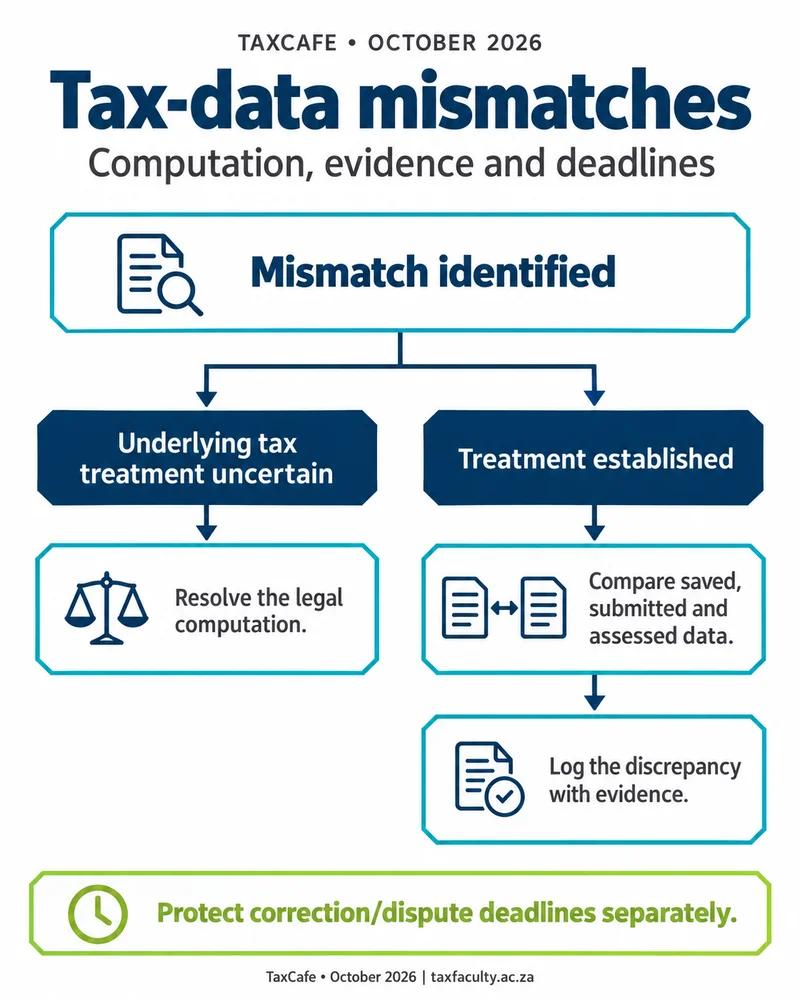
Do not move income into an inappropriate code merely to make an exemption appear. If an assessment is wrong, determine whether a request for correction, another statutory correction mechanism, or objection is appropriate. The Tax Administration Act 28 of 2011 governs those remedies. A technical support ticket does not automatically preserve an objection period or suspend payment.
Where a residence change lacks an explanation, request the relevant decision and reasons rather than assuming its cause. The file should show both the steps taken to correct the profile and the measures taken to protect the taxpayer against the resulting assessment.
Client conversation trigger: Where a system discrepancy affects tax payable, agree who will handle the technical escalation and separately diarise the available tax remedy.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Computation |
Foreign income and relief |
Cross-border earners |
Build independent schedule |
Before capture |
|
2 |
Residence |
Status and effective date |
Migrating clients |
Preserve factual and SARS record |
On change |
|
3 |
System |
Saved/submitted mismatch |
Affected returns |
Retain versions and error details |
Immediately |
|
4 |
Remedy |
Assessment consequences |
Adversely assessed clients |
Diarise correction and dispute route |
On assessment |
Retain the independent tax computation alongside the saved return, submission receipt and assessment. This gives the practitioner the evidence needed to correct a discrepancy and pursue any resulting dispute.
Related reading: Distinguishing foreign employment from independent consulting; Defining representative roles for nonresident clients; Testing the tax exemption for seafarers and yacht crew.
Frequently asked questions
Why did my foreign income disappear from my eFiling return?
Practitioners reported disappearing foreign-income fields and residence status changes at the 23 October 2026 TaxCafe webinar. Compare the saved, submitted and assessed information against an independent computation before attributing the difference to software.
Does citizenship decide tax residence?
No. Residence is a legal conclusion drawn from the facts and, where applicable, a double taxation agreement. Citizenship, immigration permission, a foreign address and tax residence are distinct matters.
What should I keep if SARS assesses a different amount?
Retain the independent computation alongside the saved return, submission receipt and assessment. That evidence supports a correction and any resulting dispute.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s Practical Guidance: Emigration and Tax webinar on demand.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).