




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Determining the tax consequences of director loan accounts
- 28 October 2026
- Corporate Tax
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Loan direction or capacity |
Main enquiry |
Control |
|
Company lends to employee-director |
Seventh Schedule benefit |
Compare actual and official interest |
|
Company lends by virtue of shareholding |
Section 64E(4), if conditions met |
Test deemed dividend and exemptions |
|
Director lends to company |
Interest income and company deduction |
Establish purpose and terms |
|
Interest is introduced |
Credit-law scope is fact-specific |
Review the agreement before changing it |
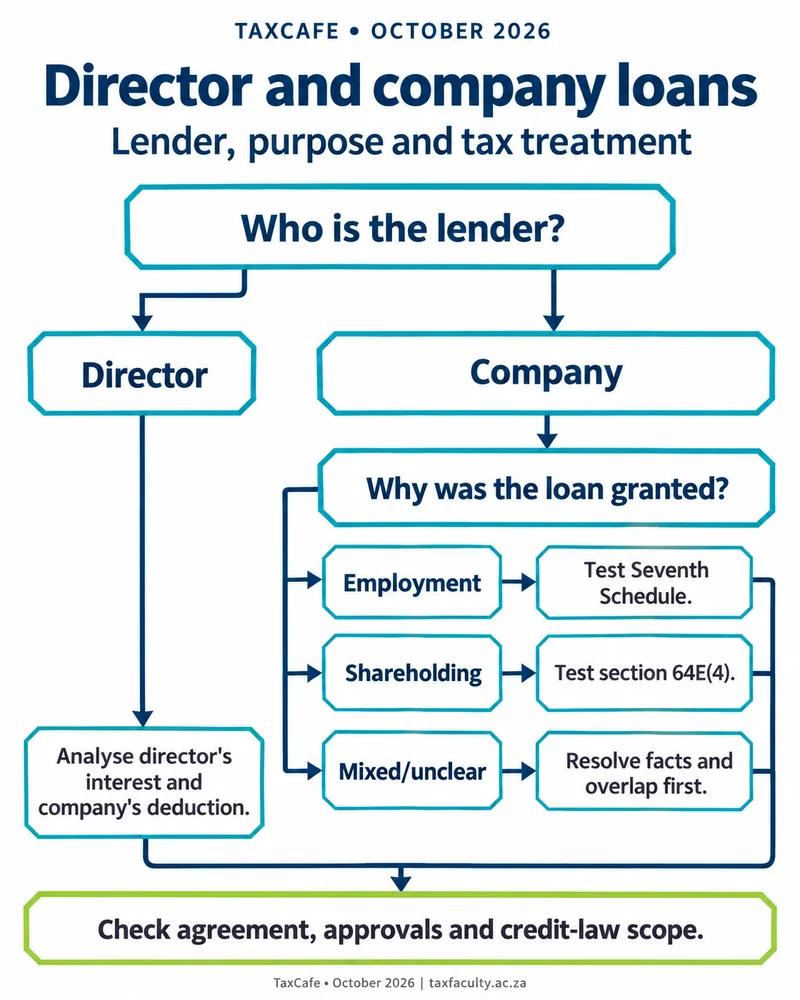
A debit director’s loan account and a credit director’s loan account are opposite transactions. In one, the company funds the individual; in the other, the individual funds the company. Advice that simply says “charge interest on the loan account” skips the first essential question.
First establish who borrowed the money and whether the individual acted as employee, shareholder or lender. Those facts determine the tax analysis. The parties can then compare their interest options and document the arrangement; the official rate is not a universal minimum contractual interest rate.
Establish the balance direction and capacity
Reconcile the account transaction by transaction. Private expenses paid by the company, salary entries, dividends, repayments and genuine advances should not remain mixed in an unexplained balance. Determine whether amounts are legally repayable and whether the account is consistently treated as debt in both parties’ records.
Where an employer makes an interest-free or low-interest loan to an employee, paragraphs 2(f) and 11 of the Seventh Schedule to the Income Tax Act 58 of 1962 may produce a taxable benefit, subject to the applicable exclusions. A director can also be an employee, but the loan’s connection to services must be considered. The South African Revenue Service (SARS) distinguishes employment-related benefits from loans made by virtue of shareholding. SARS: fringe-benefit guide.
Where the company is the borrower, the analysis changes. Interest may be income of the director, while the company must establish the requirements for any deduction. A journal entry cannot establish a retrospective contractual liability to interest where none existed. The agreement, accrual and tax treatment should be consistent.
Client conversation trigger: For every material director account, obtain a signed balance confirmation stating who owes whom, why the debt arose and in which capacity the benefit was provided.
Calculate the benefit or deemed dividend on the right basis
For an employment-related low-interest loan, the cash equivalent generally measures the shortfall between interest at the official rate and interest actually payable, applying the statutory rules and relevant periods. Use the rate changes and outstanding balances that actually apply. A single year-end balance multiplied by one annual rate can be wrong.
Section 64E(4) addresses specified debts arising by virtue of a share held in the company and can deem a dividend in specie by reference to an interest shortfall. Its connected-person, residence and other conditions must be checked. The company’s dividends-tax liability and any exemption are separate from the employee’s normal-tax computation. Where a benefit has already entered the recipient’s income, examine the exemption in section 64F(1)(l) rather than imposing both charges mechanically. SARS: comprehensive dividends-tax guide.
Illustrative example. Assume a constant qualifying loan of R500 000 for a full year, an assumed official rate of 8% throughout, and contractual interest of 3%. The interest shortfall is R500 000 × 5% = R25 000. The 8% is an illustrative assumption, not a statement of the current official rate. Whether the R25 000 is an employment benefit or a deemed dividend depends on the relevant conditions. If it is a taxable dividend in specie at 20%, with no exemption or treaty reduction, the company’s dividends tax would be R5 000.
Client conversation trigger: Model the actual-interest option against the correctly classified tax charge before the company’s year-end, using daily balances and the applicable official rates.
Document the commercial and credit law position
The National Credit Act 34 of 2005 does not apply merely because an agreement contains interest. Its scope requires analysis of the parties, the type of credit agreement, territorial connection and exclusions, including the arm’s-length enquiry in section 4. Nor does describing an arrangement as a director’s loan automatically remove it from the Act. National Credit Act.
The agreement should address repayment, interest, security if any, and what happens when employment or shareholding ends. Company authorisation and any applicable corporate-law requirements must also be addressed separately. A tax calculation does not validate an otherwise defective transaction.
Record the chosen arrangement and its tax consequences when the terms are agreed. Reclassifying private drawings only when SARS asks questions is much harder to defend.
Client conversation trigger: Where a loan has no agreement or realistic repayment plan, regularise the facts and assess the consequences before simply adding an interest journal.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Balance |
Direction and mixed entries |
Director accounts |
Reconcile and confirm debt |
Monthly/year-end |
|
2 |
Capacity |
Employment or shareholding |
Company lenders |
Record the basis of the advance |
Before calculation |
|
3 |
Tax |
Interest shortfall and exemptions |
Low-interest borrowers |
Calculate by period and balance |
Payroll/year-end |
|
4 |
Agreement |
Terms and statutory scope |
Undocumented loans |
Review contract and approvals |
Before amendment |
Retain the loan agreement with a calculation showing the treatment adopted and the balances and rates used. Review both when the loan terms, employment relationship or shareholding changes.
Related reading: Paying a connected company’s costs: when the deduction belongs nowhere on your return; Moving the business does not necessarily leave the tax debt behind; Completing payroll deregistration for each tax type.
Frequently asked questions
Must a company charge interest on a director’s loan account?
First establish whether the account is debit or credit and in what capacity the individual acted. The official rate is not a universal minimum contractual interest rate, but it affects the tax analysis.
When does a director’s loan create a fringe benefit?
Where an employer makes an interest-free or low-interest loan to an employee, paragraphs 2(f) and 11 of the Seventh Schedule may produce a taxable benefit. A director can be an employee, but the loan’s connection to services must be considered.
How should a director’s loan account be reconciled?
Transaction by transaction. Private expenses, salary entries, dividends, repayments and genuine advances should not remain mixed in an unexplained balance.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s Short Course in the Fundamentals of Corporate Income Tax.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).