




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Responding to verification requests and identifying audit
- 28 October 2026
- Tax Administration
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Feature |
Verification |
Audit |
|
Purpose |
Check declared information against supporting material |
Examine compliance through an audit process |
|
Documents |
Can include substantial relevant material |
Can also include detailed records |
|
Published duration |
SARS attempts completion within 21 business days after documents |
SARS indicates 30 business days to 12 months, potentially longer |
|
Progress communication |
Follow the selection and further-request correspondence |
Generally every 90 calendar days, subject to the applicable exception |
|
Procedural enquiry |
What was requested and by when? |
Have applicable audit notices and opportunities been given? |
|
Outcome |
Confirmation or possible revised assessment |
Findings and possible assessment, subject to procedure |
A request for bank statements does not become unlawful merely because the taxpayer has already supplied a medical, retirement or donation certificate. A certificate may establish one part of a claim while leaving payment, identity, timing or recovery unresolved. Equally, repeated document requests should be tested for relevance and handled through a clear record.
Practitioners need to establish the legal power used, the information sought and the process underway. A verification label does not permit unlimited requests, while the length of a request alone does not make it invalid. The response should address relevant evidence and any specific procedural defect.
Identify the legal power and the process actually underway
Section 46 of the Tax Administration Act 28 of 2011 empowers the South African Revenue Service (SARS) to require relevant material within its statutory framework. The volume of the request is not the sole test. Ask what tax issue is being investigated, which period is involved and how the requested material relates to it.
An audit also engages the applicable procedural requirements, including section 42. Those requirements should be considered on the substance and stage of the process, subject to the statutory exceptions. A taxpayer should not lose a procedural protection merely because correspondence uses a convenient administrative label.
Record the audit notification date and the progress-report cycle. SARS describes reports every 90 calendar days, subject to the exception where reporting would prejudice the audit. Its published duration estimates are not automatic cut-off dates. An understatement penalty can reach 200% under the statutory table, but that maximum is not the default consequence of selection or a disallowed deduction; the applicable behaviour and circumstances must be established.
SARS publicly distinguishes verification from audit. Its stated attempt to complete verification within 21 business days after supporting documents are uploaded is an administrative service expectation, not a universal statutory time limit after which every assessment or query becomes invalid. SARS: verification and audit guidance.
Client conversation trigger: For an extensive verification, obtain the selection letter and subsequent correspondence, identify the tax issues and ask SARS to clarify the process where the position is unclear.
Match each request to the supporting evidence
A retirement-annuity certificate may record contributions, but a query may concern who paid them or whether the deduction was duplicated. A medical certificate may not show reimbursements. A donation receipt may require reconciliation to payment and the taxpayer making the claim. Identify what each document establishes and supply the additional records needed to answer the request.
Prepare a short covering schedule linking every request to an attachment and page reference. Explain any difference between the certificate and the amount claimed. Where the request seeks a bank statement, supply the relevant evidence in a coherent form rather than expecting the official to infer the reconciliation from a large unexplained bundle.
If material is unavailable, state what is missing, why, what alternative evidence exists and when the balance can be provided. Seek an extension before the deadline where necessary. Do not assume that uploading some documents establishes full compliance or that an unanswered extension request has been granted.
|
Risk indicator |
File response |
|
Certificate and claim differ |
Prepare an amount-by-amount reconciliation |
|
Payment made by another person |
Explain capacity and legal basis of claim |
|
Repeated request |
Cross-reference previous submission and receipt |
|
Broad or unclear period |
Seek clarification while addressing clear items |
Client conversation trigger: Ask clients selected for verification to confirm payment sources and recoveries before submitting third-party certificates as if those certificates answer every question.
Preserve proof of submission and challenge defects precisely
Retain the document list, submission receipt and the actual files sent. Where SARS requests the same records again, identify the earlier submission reference and date, and provide a concise explanation of where the answer appears. If re-uploading is the most practical way to move the matter forward, preserve the duplication in the chronology for any later complaint.
A relevance challenge should identify the disputed item and explain why it falls outside the statutory enquiry or is unreasonable in the circumstances. It should not be a blanket refusal to provide all bank records. Material subject to legal professional privilege requires specific treatment; simply marking an accounting file “privileged” does not establish the protection.
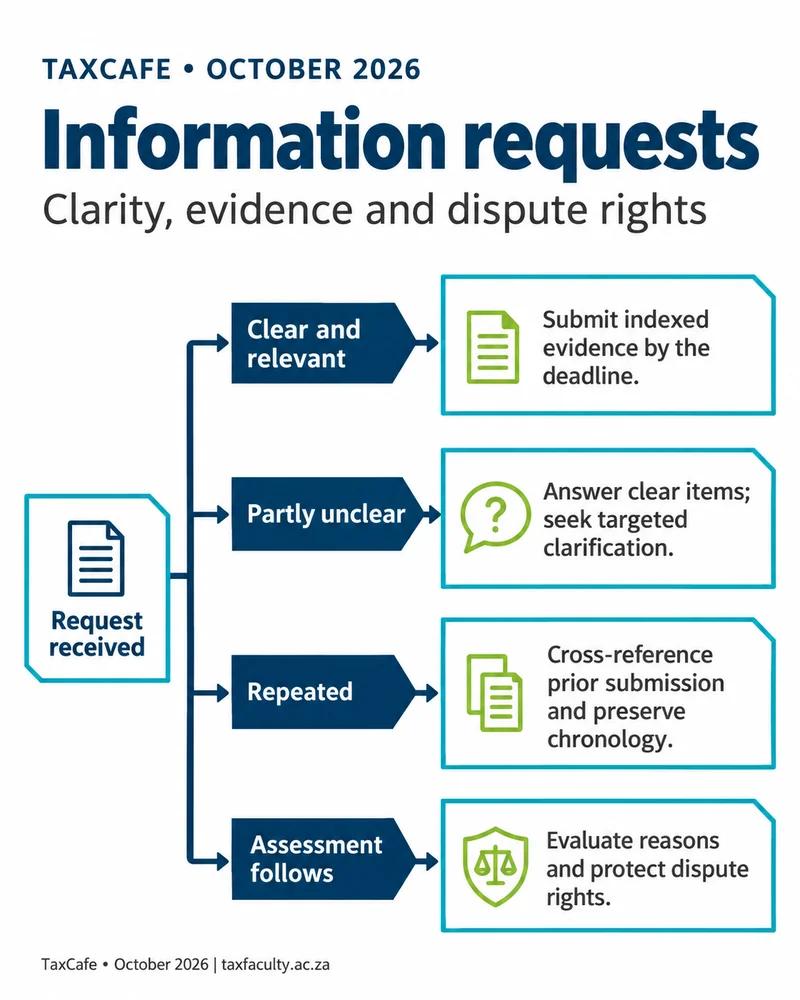
If an adverse assessment is issued, examine the reasons and the available remedy separately from the service complaint. A complaint about repeated requests does not decide whether the deduction is allowable, and it does not automatically suspend collection or extend the objection period.
Client conversation trigger: Where verification remains unresolved, agree who will manage the evidence, the service escalation and any resulting assessment dispute, with separate deadlines for each.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Process |
Verification or audit |
Selected taxpayers |
Identify power, stage and notices |
On selection |
|
2 |
Evidence |
Certificates are incomplete proof |
Deduction claimants |
Match request to indexed evidence |
Before deadline |
|
3 |
Repetition |
Documents requested again |
Delayed cases |
Preserve receipts and chronology |
Each submission |
|
4 |
Rights |
Unclear or excessive request |
Affected taxpayers |
Make a precise challenge |
Promptly |
|
5 |
Assessment |
Separate remedy |
Adversely assessed clients |
Diarise reasons and objection |
On assessment |
Keep an indexed response and a dated record of every request, submission and decision. That file should support both the tax position and any challenge to the procedure followed.
Related reading: Reconciling bank deposits before disputing an assessment; Protecting dispute deadlines while pursuing SARS complaints; Estimated assessments: challenge the calculation and prove the alternative.
Frequently asked questions
What is the difference between a SARS verification and an audit?
SARS publicly distinguishes them. It aims to complete verification within 21 business days after documents are uploaded, while audits may take 30 business days to 12 months or longer, with progress reports generally every 90 calendar days.
Can SARS ask for bank statements if I already gave a certificate?
Yes, potentially. A certificate may establish one part of a claim while leaving payment, identity, timing or recovery unresolved.
Does a verification become invalid after 21 business days?
No. That is an administrative service expectation, not a universal statutory time limit after which every query becomes invalid.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s SARS Dispute Resolution: A Focus on Objections and Appeals webinar on demand.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).