




CATEGORIES
- (3)AI & Technology
- (52)Accounting & Financial Reporting
- (1)Accounting for Income Tax
- (1)Assessed losses
- (38)Blogs
- (4)Business Advisory
- (8)Capital Gains Tax
- (1)Capital Gains Tax - Individuals Tax
- (1)Capital Gains Tax Implications of Trusts
- (2)Case study: Home office expense
- (1)Case study: Travel allowances
- (1)Company Formations
- (10)Compliance
- (141)Corporate Tax
- (15)Customs and Excise
- (2)Deceased Estate
- (1)Deductions Pre-trade and prepaid expenses
- (1)Deregistration
- (2)Employer and Employee (PAYE and UIF Specific)
- (1)Estate Duty
- (1)Events / Webinars
- (11)Faculty News
- (2)Farming
- (177)Individuals Tax
- (1)Input - Customs Duty
- (3)Interest
- (23)International Tax
- (1)Nature of the rights of beneficiaries
- (1)Notional input tax
- (10)Payroll
- (1)People & Practice Management
- (2)Practical Payroll
- (1)Professional Ethics
- (2)Provisional tax (Link with other Taxes)
- (4)SARS Issues
- (178)Tax Administration
- (2)Tax Administration Part 2B: Resolving Problems with SARS using the Tax Ombud
- (1)Tax Administration Part 3B Dispute Resolution - Objection and appeal
- (8)Tax Dispute Resolution
- (1)Tax Opinions
- (3)Tax Update
- (1)Tax implications of loans to trusts
- (1)Tax residence
- (1)Tax returns and payments
- (3)Transfer-Pricing
- (1)Trust Income / Gain Allocations
- (1)Trust types and income allocations
- (12)Trusts
- (88)VAT
- (3)VAT periods
- (1)Wear and tear allowances
- (14)Wills, Estates & Succession
- (1)Zero Rated
- (2)eFiling
- Show All

Completing the diesel refund registration transition
- 28 October 2026
- Compliance
- Dr Stiaan Klue
Source: TaxCafe, Carmen Westermeyer CA(SA), October 2026. Available on Webinar-on-Demand: TaxCafe with Carmen Westermeyer - October 2026
At a glance
|
Development |
Previous arrangement |
Published change |
Relevant date |
|
Registration |
Linked to VAT registration |
Separate diesel registration platform |
Implemented 18 September 2026 |
|
Existing users |
Existing diesel registration records |
New registration action remains necessary |
Current transition |
|
Entity profile |
Unresolved profile data could remain |
Validate, confirm and merge profiles for access |
SARS update: 21 October 2026 |
A diesel-refund entitlement and access to the system used to administer it are separate matters. A business may undertake qualifying activities yet be unable to complete registration because its legal-entity profile is incomplete. Equally, a successful registration does not establish that every litre purchased qualifies for a refund.
The South African Revenue Service (SARS) implemented its separate diesel-refund registration platform on 18 September 2026. Its 21 October update requires relevant entity profiles to be validated, confirmed and merged before access. Existing users need to complete the transition and retain their claim history; automatic migration should not be assumed. SARS: Diesel Refund Scheme.
Resolve the entity before the application
Registration work should begin with the legal person that purchases and uses the fuel. Trading names, group companies, branches and the practitioner’s eFiling profile can obscure the identity of the claimant. Establish which person operates the qualifying activity and holds the supporting invoices and usage records. A group’s internal allocation cannot, by itself, transfer another entity’s refund entitlement.
The application file should contain the current registration particulars, representative’s authority and a record of the profile statuses. Where separate records refer to the same entity, resolve that duplication through the official maintenance process. Creating a second identity to bypass a validation problem risks splitting the claim history and making later verification harder.
SARS identifies eFiling and Customs and Excise branches as application channels. Its Online Query System also supports specified enquiries and document requests. The appropriate channel should be selected for the actual problem: an access issue, an incomplete application or a claim question. Retain the acknowledgement and the final registration outcome rather than relying on a screenshot showing only that information was captured.
Client conversation trigger: Contact every existing diesel-refund client and confirm that a named person owns the transition task, with evidence of the entity’s profile status and registration outcome.
Preserve the link between purchase and qualifying use
The governing framework is the Customs and Excise Act 91 of 1964, read with the relevant provisions of Schedule 6 and its notes. Eligibility is activity-specific. The accounting description “diesel” does not establish the statutory use, and the fact that a business operates in agriculture or mining does not make all its fuel consumption eligible.
The working record should connect supplier invoices, deliveries, storage movements, issues to equipment and the activity performed. Where a common tank serves several activities, a total purchase figure is inadequate. The allocation method should identify excluded or private consumption and reconcile opening stock, purchases, issues and closing stock. Unexplained differences should be investigated before a claim is prepared.
Illustrative example. A business purchases 10 000 litres. Its reconciled records show 6 000 litres used in activities that qualify under its scheme category, 2 500 litres used in activities that do not qualify and 1 500 litres still in stock. The purchase total is not the claimable-use total. The calculation must begin with the 6 000 litres and then apply the category’s current qualifying percentage and refund rate. This example assumes eligibility; it does not establish it.
Client conversation trigger: Ask mixed-use operators to demonstrate how a litre moves from the supplier’s invoice to the qualifying activity. Reconstruct missing allocations before submitting the next claim.
Reconcile claims during the registration transition
A practical transition file should preserve the old registration particulars, outstanding claims, query history and reconciliations immediately before the move. Record which transactions have already been claimed and which remain unclaimed. Otherwise, changing systems can produce duplicate claims or omissions that surface months later.
The new registration process should not be treated as retrospective permission to claim fuel outside the governing conditions. Nor should a practitioner assume that every older website paragraph describes the same stage of implementation. Read dated notices together with the applicable scheme rules, and obtain clarification where the application status and the published process conflict.
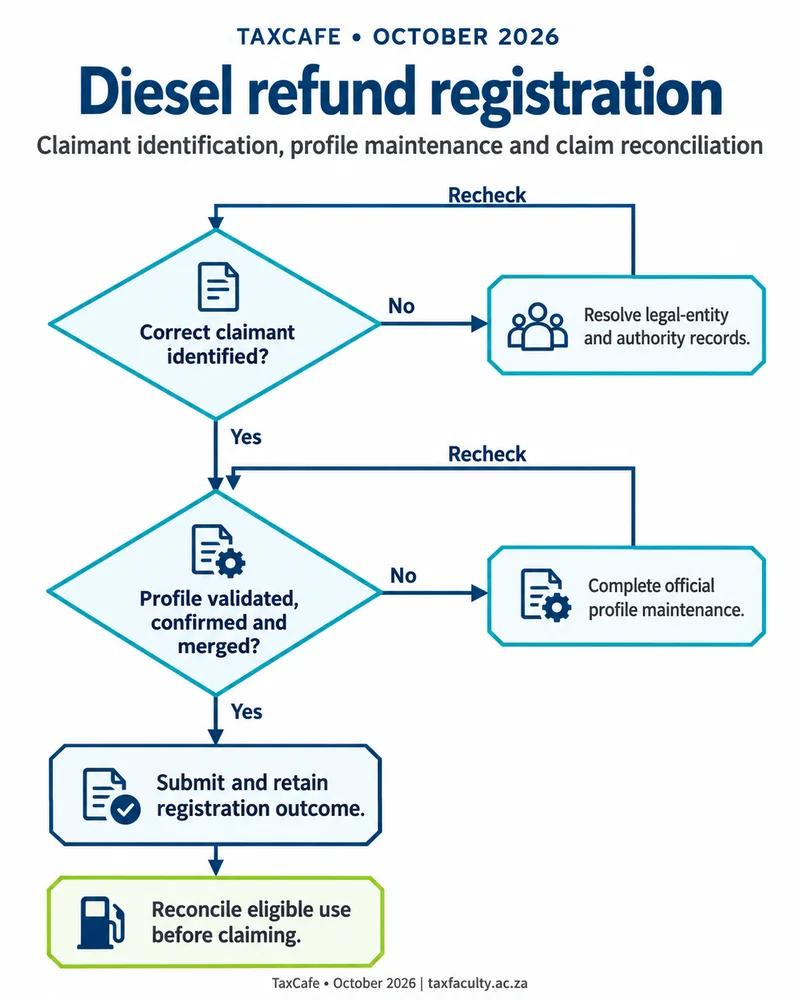
For an operational interruption, log the error, date and application reference, together with the steps already taken and the assistance required. That makes escalation useful and preserves the explanation for delay. It does not replace the underlying fuel records.
Client conversation trigger: For clients with unresolved registration access, agree an interim recordkeeping process so that the administrative problem does not become an evidential problem.
Practitioner action checklist
|
# |
Area |
Issue |
Clients affected |
Action required |
Timing |
|
1 |
Profile |
Entity validation |
Existing and new users |
Resolve profile statuses |
Before registration |
|
2 |
Authority |
Correct claimant |
Groups and branches |
Confirm entity and representative |
Before application |
|
3 |
Evidence |
Eligible consumption |
Mixed-use operators |
Reconcile purchases, use and stock |
Each claim |
|
4 |
Transition |
Duplicate or missed claims |
Existing users |
Preserve old-to-new reconciliation |
During migration |
Close the transition task when registration is confirmed and outstanding claims reconcile to the retained records. For each claim, reconcile qualifying consumption and separately identify fuel used outside the qualifying activity.
Related reading: Reconstructing liability after backdated VAT registration; VAT modernisation: prepare the transaction data before buying the technology; Repairs, improvements and recoveries: build the deduction from the work performed.
Frequently asked questions
Will my diesel refund registration migrate automatically to the new SARS platform?
Automatic migration should not be assumed. SARS implemented its separate platform on 18 September 2026, and its 21 October update requires entity profiles to be validated, confirmed and merged before access.
Does diesel refund registration mean all my diesel qualifies?
No. Registration does not establish that every litre purchased qualifies for a refund. Each claim should reconcile qualifying consumption and separately identify fuel used outside the qualifying activity.
Can a group company claim the diesel refund for another entity?
The claimant is the legal person that purchases and uses the fuel in the qualifying activity. A group’s internal allocation cannot, by itself, transfer another entity’s refund entitlement.
Build your expertise: to apply these principles in practice, explore The Tax Faculty’s Microlearning Course: Customs.
About the author
Dr Stiaan Klue is Executive Dean and CEO of The Tax Faculty. He was the founding CEO of the South African Institute of Taxation (SAIT) and is the founding author of Silke on Tax Administration (LexisNexis).